This month last year, Glass Lewis announced that it will be moving away from “singularly-focused research and vote recommendations based on its house policy.” Last month, the proxy advisor announced that it has now opened a comment period on the four perspectives that will underpin its research beginning in September 2027 and is soliciting feedback from both institutional investor and corporate stakeholder groups. Pay Governance recently released a viewpoint regarding how this shift is likely to impact say-on-pay votes.
The four perspectives share a common compensation foundation. All perspectives maintain core expectations around reasonable pay levels, pay-for-performance alignment, disclosure quality, severance practices, incentive design, non-employee director pay programs, and other key governance topics.
The major differences among the models lie in how the perspectives may weigh performance, sustainability, and stakeholder outcomes. Business Fundamentals could treat top-quartile relative TSR as an explicit mitigating factor, allowing greater tolerance for higher pay or certain design features. Sustainability Focused may instead expect material sustainability considerations in performance measurement and assess whether pay outcomes align with the broader stakeholder experience. Thus, a company’s Say on Pay proposal may draw different recommendations—particularly when pay is high, relative TSR is strong, sustainability metrics are absent, or stakeholder and executive outcomes diverge [. . .]
The proposed Glass Lewis pivot on advisory reports changes the lens through which programs are viewed, but not the fundamentals. Compensation committees should continue to design pay to align with business strategy, performance, and long-term value creation, supported by rigorous governance and an investor-informed rationale. The best-positioned companies will not attempt to tailor their programs to each Glass Lewis perspective; rather, they will understand their shareholders and explain why their programs are right for their business.
It reiterates that this announcement is part of a broader trend where “investor policies—and not one proxy advisor standard—may increasingly drive voting decisions.” It also notes that pay disclosure may be fundamentally transformed by proposed and expected SEC rulemaking that could reduce and streamline required disclosures—and even make many more companies eligible for scaled disclosure and other accommodations, like omitting a say-on-pay proposal. This could raise the stakes for some companies (if investors voice their perspectives through “withhold” votes on compensation committee members, for example) and increase the need to provide more context and address more perspectives in your disclosures, even as disclosure requirements become less prescriptive.
As Liz shared on TheCorporateCounsel.net yesterday, Walt Disney World celebrated its 55th anniversary last week and marked the occasion by looking back at what it has been through since 1971 and how much has changed along the way. Through all of it, the magic has endured! That feels on point for those of us working in corporate governance and executive compensation as well. So the timing is right to gather at our 2026 Proxy Disclosure & 23rd Annual Executive Compensation Conferences next Monday and Tuesday, October 12th and 13th (less than one week away!), in Orlando and virtually, to discuss perennial issues plus the many regulatory and market developments companies are navigating right now. Getting together with a group of people with a shared passion for corporate governance, quality disclosure and pay-for-performance always feels magical to me!
Here’s a look at some of the hot topics our experienced speakers will be addressing. You’ll walk away with a better understanding of the practical impact these developments may have on companies, disclosures and boards – and how all the moving pieces fit together.
On October 12th, our 2026 Proxy Disclosure Conference will focus on (you guessed it) proxy disclosures – starting with an interview with Corp Fin Deputy Director Christina Thomas. Among other topics, we’ll discuss the fate of shareholder proposals, the current shareholder activism environment, common mishaps (and how to avoid and resolve them), tokenization of securities and other market developments, SEC proposals on registered offering reform and filer status, shareholder engagement and voting, and advising boards during times of uncertainty.
On October 13th, our 23rd Annual Executive Compensation Conference turns to (yep!) executive pay, including potential changes to the SEC’s compensation disclosure rules, the potential expansion of scaled disclosure, equity design (including long-vested RSUs), special awards, executive and director pay trends, and perks and executive security. We will close the conference with the popular panel “Navigating ISS & Glass Lewis” featuring a practical conversation with representatives from both proxy advisors on disclosures and practices that will help (or hurt) your cause on say-on-pay, compensation committee elections and equity incentive plan approvals, moderated by Davis Polk’s Ning Chiu.
For those attending in person, the magic actually starts a little early! We’ll have a welcome reception Sunday, October 11th, from 4:30–6:00 p.m. in the Orange Foyer. And the networking opportunities continue on the evening of the 12th at the NASPP opening celebration immediately after Monday’s programming.
As always, the two days are bundled together, and you can join us in person at the Hilton Orlando or virtually. And in addition to live and on-demand access to all of the CCRcorp sessions, Conference attendees get exclusive access to our Course Materials – which are up on the conference platform and app now and include unique & practical bullet points on the topics our speakers will be covering. The Course Materials and on-demand replays are invaluable resources to refer back to as proxy season approaches!
Act Now: The Conferences begin next Monday, October 12th. With 14 sessions over 2 days, you’ll walk away with action items to help support director elections and say-on-pay, see around corners for changes to rules and market mechanics that affect companies, and avoid costly mistakes. You can still register. Sign up online, email info@ccrcorp.com or call our team at 800-737-1271 today.
Lastly, if you have registered, remember that your unique access link and attendance instructions will be emailed to you from no-reply@events.ringcentral.com. Here’s more detail on what to watch for.
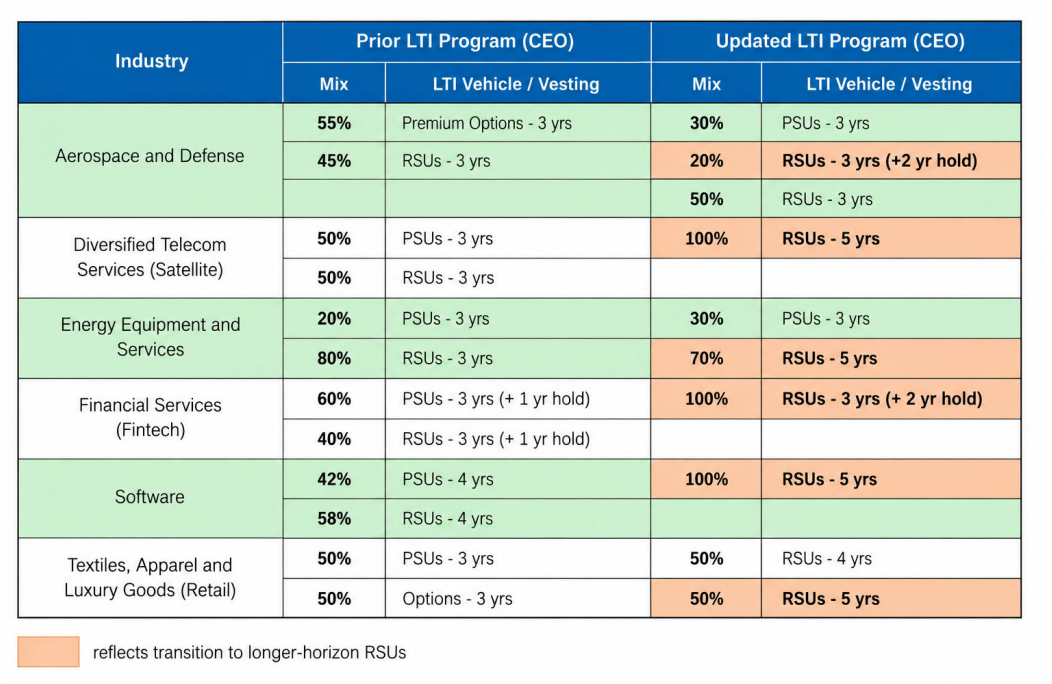
With ISS’s latest policy updates loosening the proxy advisor’s preference for at least 50% of LTI in PSUs as long as time-based equity meets its long-term parameters, we already knew that some companies have been considering making a change. FW Cook reviewed forward-looking disclosures in 2026 proxy statements to see if any companies have already committed to taking the plunge. They found at least six companies that have already disclosed a transition, as summarized below.
They highlighted a few considerations and takeaways from these early movers:
– Many of them had one thing in common: they are in cyclical, seasonal or volatile businesses.
– Companies shouldn’t think of the decision as a binary one. Reducing PSU weighting and introducing longer vesting RSUs might be the right first move for some companies.
– The shift can create vesting gaps, and companies should model the transition for each executive to understand the impact.
It’s possible that pay-versus-performance disclosure requirements as we currently know them are going to be short-lived, but the ship hasn’t sailed yet – and in the meantime, people are using the data. In this article, Stephen O’Byrne of Shareholder Value Advisors makes the argument that PVP information is much more useful than SCT disclosure that focuses on grant date fair value – and shows that conventional wisdom about pay programs may be misguided. Here’s an excerpt (also see this HLS blog):
The conventional wisdom is that companies can achieve the three basic objectives of executive pay – providing strong incentives to increase shareholder value, retaining key talent and limiting shareholder cost – if they have a high percent of pay at risk with target pay set at the peer group median. The conventional wisdom accepts a low correlation of target (and grant date) pay with relative TSR but argues that post-grant date changes in the value of unvested equity provide a strong incentive to increase shareholder value.
For 70 years, proxy statements only reported grant date pay and there was no way to test the truth of the conventional wisdom. The new PvP disclosure provides, for the first time, the data to test the conventional wisdom and it shows that the conventional wisdom doesn’t work well for many companies.
For more than half, relative TSR explains less than 50% of the variation in relative mark to market pay. A third of companies have very weak incentives – a 1% increase in relative shareholder
wealth increases relative mark to mark pay by less than 0.2%. The analysis we do with the PvP data, i.e., plotting relative pay against relative TSR to quantify five pay dimensions, provides a guide path to better pay design. It provides a clear goal, showing that there is a simple pay plan with annual grants of performance shares that provides a perfect correlation of relative pay and relative performance with pay leverage of 1.0 and a zero pay premium at peer group average performance. It also provides a way to monitor progress toward the goal: benchmarking pay dimensions – alignment, incentive strength, relative pay risk and performance adjusted cost – to measure progress in improving the company’s pay plan.
Stephen walks through a couple of case studies in the article to show how PVP can be used to measure alignment across the dimensions he identified. He also outlines how it could be used to measure the impact of CEO pay and stock ownership on future shareholder returns. I don’t know that every company would have the resources to perform these analyses, but some are already doing so anyway for existing models – and Stephen suggests that pivoting to the PVP data would ultimately simplify compensation-setting and voting. First, though, you have to overcome the mental block of “new maths to math.”
The article suggests ways that investors could use PVP in say-on-pay voting guidelines, and says that the existing ISS models that many companies have designed around have resulted in misaligned pay in some cases. Meredith blogged earlier this year about how some investor models may already be evolving…
With underwater options in the news, companies that award this form of equity may want to consider what to do if the awards were granted at a market peak and/or the company’s stock price has been declining. This Semler Brossy newsletter points out that this issue can affect the broader executive team – not just the CEO. It suggests questions for boards:
1. Where in the organization are options best aligned with the compensation philosophy?
2. Even if options are underwater now, what is the upside potential under various rebound scenarios, and how do we best communicate that to recipients?
3. If your options are meaningfully underwater, is an exchange program worth exploring, or does the signal it sends outweigh the benefit? Related resource: What to do about deep underwater stock options.
4. If you were to move away from options, what vehicle would better capture performance without abandoning program rigor?
The newsletter cites to a recent study that found roughly a third of stock options granted since 2023 are now underwater – especially in retail and healthcare. The Semler Brossy team also notes that only about 45% of S&P 500 companies are granting options these days – but they haven’t disappeared. With such a big potential upside, they are still a vehicle at companies large and small. See our “Stock Options” Practice Area for more resources.
Share counting on Form S-8 is not always a straightforward exercise. In fact, we have an entire checklist explaining how to do it. But sometimes, even with the best of effort, mistakes happen. What happens then?
Yesterday, the SEC posted this administrative proceeding order about a company that discovered it had sold shares pursuant to an ESPP in excess of the number registered on its Form S-8 registration statements. My stomach always sinks when I read about over-issues – record-keeping may be out of the securities lawyer’s hands, but any clean-up will be in their court.
I was relieved to see that in this case, the company handled it well and the story had a (relatively) happy ending – with a cease-and-desist order and no civil penalty. According to the SEC, here’s what led to the over-issue:
– During the Relevant Period, the company did not have policies addressing the need to keep an accurate count of shares sold under the ESPP. While the company had legacy procedures for operating the ESPP and for preparing its annual proxy statement (which, as described in the order, included a disclosure of shares remaining for sale under the ESPP), these procedures, implemented prior to the Relevant Period, were not adequate to ensure that the company kept accurate records of shares sold under the ESPP.
– The company hired a third party to administer the ESPP – that party committed, among other things, to “maintain share lot history” and provide regular reports to the company. There were monthly letters about the purchases and sales, but the company didn’t use those letters to track the shares remaining available for issuance.
– During the Relevant Period, once a year, consistent with its legacy procedures, in connection with the preparation of its proxy statement, the company asked the service provider to indicate how many shares it had sold under the ESPP in the most recent calendar year. The company subtracted this figure from the “shares remaining” figure on the latest proxy statement, and input the result into the new proxy statement. The company did not otherwise track the number of shares remaining for sale under the ESPP during the Relevant Period. At some point, this figure became inaccurate.
– In connection with preparing a new S-8, the company asked the service provider to provide a complete record of all shares sold under the ESPP since inception. That spreadsheet indicated that the company had sold shares in excess of the aggregate number of shares it had registered on the Form S-8 registration statements.
Here’s what the company did next:
– Upon discovery of the violation, the company promptly suspended the ESPP and conducted an investigation.
– The company then self-reported the violation to the Commission and voluntarily initiated a rescission offer to provide compensation to all affected current and former employees for all shares sold in excess of the ESPP registration, even including as eligible securities for which actions would otherwise have been barred under Section 12(a)(1) of the Securities Act.
– Following the self-report, the company also voluntarily produced relevant factual information and documentation to the Commission staff.
The order is a good case study on firming up controls. And while every enforcement proceeding is unique and YMMV depending on many circumstances, the company’s response also seems to provide a good roadmap for addressing an S-8 overissue.
At our upcoming “Proxy Disclosure & 23rd Annual Executive Compensation Conferences,” I’ll be moderating a “campfire” discussion of scary securities law stories – with Howard Dicker of Weil Gotshal, JT Ho of Cleary Gottlieb, and Allison Handy of Ashurst Perkins Coie. These seasoned practitioners will regale us with their own tales of over-issues and other mishaps they’ve seen – and give pointers on how to resolve them. Join this session in Orlando (or virtually) on October 12th at 11:30 a.m. ET – it will be sure to put you in the Halloween spirit! You can still register for the Conferences – online, by email to info@ccrcorp.com or by calling our team at 800-737-1271. Don’t wait – the Conferences are only two weeks away!
Just two short weeks away, and the anticipation is high! Our “Proxy Disclosure & 23rd Annual Executive Compensation Conferences” are happening in Orlando on Monday, October 12th and Tuesday, October 13th (and virtually, nationwide). If you haven’t already registered, there is still time to do so – but don’t delay! You will not want to miss our action-packed agenda full of practical tips on what you need to know and do in response to all of the SEC’s rulemaking and the current disclosure and corporate governance environment. Here are a few notes:
– Make sure to get in as soon as possible – the hotel is nearly full. Book your room here!
– After you’ve registered, check your email for a message from CCRcorp – via no-reply@events.ringcentral.com (our conference platform and app provider) – This email confirms your registration and contains your unique link to access the conference platform. Meredith shared more detail in this blog.
– Come say hi at our reception Sunday night, October 11th, and at the NASPP welcome reception on Monday night, October 12th. Get the details in this blog.
To register for the conferences, visit our online store, email info@ccrcorp.com or call our team at 800-737-1271 today.
BlackRock Investment Stewardship (BIS), which is responsible for stewardship activities related to BlackRock index funds, has published its Global Voting Spotlight for the period of July 1, 2025 to June 30, 2026. Here are the key executive compensation-related takeaways from the summary of its voting activity:
– BIS voted on 18,705 executive compensation (management and shareholder) proposals (approximately 12%).
– Concern about the alignment of executive compensation with shareholders’ long-term financial interests was the fourth most common reason BIS cited for not supporting director reelections (impacting 1,063 proposals categorized as director elections at 596 companies).
– In the U.S., pay concerns were driven by “large outside-of-program awards without a strong strategic rationale, limited linkages between pay outcomes and long-term financial performance, or insufficient explanation of how compensation program design supported corporate strategy.”
– BIS supported approximately 84% (15,780 out of 18,705) of compensation-related management proposals overall and approximately 90% in the Americas.
– BIS’s support was “driven by many companies’ clear articulation of how their policies align with shareholders’ long-term financial interests, particularly around how short- and long-term incentive plans complement one another and are effective in rewarding executives who deliver long-term financial value.”
FW Cook recently reviewed incentive plan practices among the Top 100 publicly traded REITs. They found that REITs “generally align with broader-market conventions in overall plan structure, but differ meaningfully in the selection, weighting and application of performance measures.” Here are a few of their key findings:
FFO remained the defining annual incentive measure, used by 73% of REITs, while 58% used other profit measures such as earnings before interest, taxes, depreciation and amortization (EBITDA), net operating income (NOI), earnings per share (EPS) or funds available for distribution (FAD).
Individual performance was also prevalent (61%), and approximately half of REITs incorporated strategic or operational measures.
Non-financial measures represented an average 26% of annual incentive weighting among REITs versus 19% in general industry.
Moreover, REITs overwhelmingly incorporated individual and strategic performance as separately weighted metrics rather than as modifiers, in contrast to the more modifier-oriented approach prevalent in general industry
Stock options were rare (2%), compared with 38% prevalence among the Top 250 general industry companies—a notable distinction given the importance of dividends to REIT shareholder returns.
Ninety-four percent of REITs used rTSR, reflecting the sector’s emphasis on measuring shareholder returns relative to market or industry conditions. Unlike general industry, where rTSR was more frequently used as a modifier to internal performance measures, 90% of REITs using rTSR employed it as a stand-alone metric. Fifty-eight percent compared performance against an index, 30% used a custom performance peer group, and 12% used both. Percentile ranking was the predominant measurement methodology, although approximately one-quarter used an rTSR differential approach that measured the magnitude of outperformance or underperformance versus a benchmark.
“The proposing release discusses the scope of the Commission’s authority under Section 14(a) of the Exchange Act and explains that Rule 14a-8 should be rescinded because it exceeds the Commission’s statutory authority. The Commission also has independent policy reasons for proposing to rescind the rule. First, many of the justifications that were originally provided to support adoption of Rule 14a-8 either have not been substantiated in practice or are less compelling today.
In addition, Rule 14a-8 also has had, and will continue to have, certain unintended consequences that further undermine any justification for retaining the rule:
Rule 14a-8 has become a mechanism for influencing the interactions between companies and their shareholders in ways that are inconsistent with the rule’s original purpose.
The existence of Rule 14a-8 places the Commission in the position of making judgments about the application of state law that are best left to other actors.
The presence of a federal rule has inhibited the development of state law and private ordering.”
The proposal would also amend Rule 14a-4(c) to address the issues companies face related to discretionary authority when a shareholder proposal isn’t included in a company’s proxy statement, which may be more common after the repeal of Rule 14a-8. The proposing release says:
“[I]f current Rule 14a-4(c)(2) were to remain in effect, more companies may feel compelled to include a proponent’s proposals in the company’s own proxy materials to obtain proxy voting authority from shareholders on the proposals [. . .] Under the proposed amendments, a proponent’s proxy card could include the company’s nominees, management proposals, and the proponent’s proposals, while the company’s card could solely include the company’s nominees and management proposals. The company could then exercise discretionary voting authority to vote proxies it receives against the proponent’s proposals, other than for proxy cards the company receives on which shareholders have checked the proposed [. . .] check box [. . .] that would provide shareholders an option to prohibit the company from exercising discretionary voting authority on proposals omitted from the company’s proxy card.”
“A proponent’s independent solicitation would no longer prevent the company from exercising discretionary voting authority over all proxies it receives. Instead, each shareholder would decide whether to allow the company to vote that shareholder’s shares on the omitted proposal.”
Without Rule 14a-8, determining when companies must include shareholder proposals in their proxy materials would be left to state law and potentially companies’ governing documents, and “the transition period may be bumpy,” as Commissioner Peirce acknowledges in her statement. That’s because, as the fact sheet notes, “the presence of a federal rule has inhibited the development of state law and private ordering.” Gibson Dunn has discussed this in detail, saying “many state corporate law aspects of shareholder proposals remain unclear or unsettled,” including in Delaware, and different states may take different approaches.
As Goodwin notes, frameworks will eventually be developed governing “who may submit proposals, which matters are permissible for a shareholder vote in those proposals, and when inclusion in a company’s proxy statement is required” through private ordering and state law. Meanwhile, hearing words like “bumpy” and “unclear or unsettled law” makes me think of the Wild West. It may get worse before it gets better. Saddle-up!
The comment period will be open for 60 days following publication in the Federal Register.
Side note: We were pleased to see one of our blogs and remarks from the 2024 Proxy Disclosure & Executive Compensation Conferences cited in the discussion of Rule 14a-4(c). Special thanks to our former editorial colleague, Emily Sacks-Wilner,for pointing this out while I was still digesting the fact sheets! She is so on top of things!
As Dave shared yesterday, we now know the comment period will close on November 20. I’d encourage everyone to read Dave’s blog as well because he addresses the most common questions he’s received since the proposal came out.
I’ll also reiterate Dave’s suggestion to sign up to attend our 2026 Proxy Disclosure Conference and the 23rd Annual Executive Compensation Conference on October 12-13, either in person in Orlando or via webcast, for an in-depth discussion of where the experts expect things to go from here during the panel “The Fate of Shareholder Proposals.” And, as always, we have an entire day of content dedicated to setting and disclosing executive compensation and many opportunities to network with your peers. You can register online or contact us at info@CCRcorp.com or 1-800-737-1271. We look forward to seeing you in October!