Director deferred compensation programs have been popular for a long time, but this WTW alert says they’re far from universal. There may be opportunities there because deferred compensation programs “can strengthen a non-employee director pay program by providing financial planning flexibility while reinforcing long-term shareholder alignment — often without increasing underlying compensation levels.”
After reviewing disclosures of S&P 500 companies over the five-year period of 2020-2024, WTW found that 70% of the S&P 500 had a director deferral program in 2024. Deferral programs are less widely-adopted in mid- to small-cap companies.
Design also matters. Over half permitted directors to defer cash and equity compensation in 2024. Meanwhile, 32% permitted cash and 14% allowed equity deferrals.
Cash deferrals can help manage income timing and tax planning.
Equity deferrals may preserve or extend exposure to company stock and reinforce alignment with shareholders.
Programs that permit both cash and equity deferrals provide the broadest planning flexibility, and large-cap company prevalence of cash and equity deferral programs grew to more than 50% in recent years.
While shareholders generally don’t have a problem with them, there is a trade off that companies are balancing in that deferral programs mean added complexity and recordkeeping. The WTW team suggests that companies without deferral programs give them some thought and companies with deferral programs consider whether the design continues to be appropriate. They also share some questions to consider for any boards considering a new program or refreshing an existing program.
As John shared on TheCoprorateCounsel.net on Friday, Corp Fin just issued six new and two revised CFIs. With the exception of one CFI addressing the timing of Form 4 filings for transactions on a foreign stock exchange, the CFIs cover Form S-8 and Rule 701-related topics. As Broc said on Cooley’s Governance Beat blog, there are some “biggies” here. More from Broc:
One biggie is Question 271.28 under the ’33 Act Rules, which is a new CFI allowing companies to move outstanding pre-IPO compensatory awards that were originally granted in reliance on an exemption from registration onto a Form S-8 after the IPO.
Two other related biggies are Question 271.29 under the ’33 Act Rules and Question 126.14 under the ’33 Act Forms, which liberalize the treatment of assumed awards in acquisitions as assumed awards held by former target employees can now be covered by Form S-8 for public-company buyers or Rule 701 for eligible private-company buyers.
Also check out Question 126.46 under the ’33 Act Forms under which Corp Fin will allow companies to apply the filing fees associated with securities underlying forfeited RSUs to future registrations of offers and sales of securities underlying the RSUs. As a result, companies should no longer need to register extra shares on Form S-8 simply to account for shares underlying forfeited RSUs that return to the plan pool.
And Question 126.47 under the ’33 Act Forms is notable as well, under which Corp Fin will allow companies to register restricted stock and RSUs no later than the date of vesting, so long as a company was eligible to use Form S-8 on the date of grant. This brings the treatment of restricted stock and RSUs closer to the existing treatment of options under Question 126.02, which permits shares underlying options to be registered on Form S-8 at any time before exercise – regardless of when the options became exercisable.
Broc notes that some of this guidance follows engagement between the ABA’s Joint Committee on Employee Benefits (JCEB) and the Staff. People who have been working in executive compensation disclosure for a while know that the JCEB used to meet with federal agencies every spring to share common questions. The JCEB would share notes from the meeting, with the questions asked and the Staff’s response, until the format of the meeting changed in 2015. I believe the meetings were then suspended for some time due to COVID. So big thanks to the JCEB for re-engaging with the Staff and to the Staff for its open door policy, attention to pain points and willingness to issue guidance!
Though they’re old, I do still (for now!) find myself referencing pre-2015 JCEB notes from time to time. In case you need to too (or are interested in the history), keep in mind that we have those notes posted here on CompensationStandards.com (subject to the disclaimer at the top of the page), and they’re still available on the JCEB page on the ABA’s website.
I sure have been learning a lot this week at our Executive Compensation Conference and the NASPP Annual Conference – including creative approaches to equity awards. For example, time-based RSUs are attractive for their simplicity and predictability, but they aren’t perfect. In this memo, the Infinite Equity team outlines the challenges that can arise, such as:
1. “Rest & vest” criticism – shares vest regardless of whether shareholder value has increased, held flat, or declined, which can create misalignment between pay and performance and may raise questions with shareholders.
2. Settlement during challenging times – companies must satisfy employee tax withholding at each vest date, which can affect the market price if it involves large sell-to-cover transactions and can affect the balance sheet if the company uses net share withholding. If the company’s stock price is depressed or trading at low volumes, vesting events can have negative consequnces to the company.
3. Grant guideline confusion – for awards based on a dollar value at grant date, an employee that receives shares at a time the stock price is materially lower, may feel they are not getting the full value that the parties understood the award to represent.
The memo makes the case that “price-protected” RSUs could address these challenges – not by adding a performance condition, but by deferring delivery until the stock price recovers. Here are the key takeaways:
– Traditional time-based RSUs vest on schedule no matter what happens to the stock price. In our analysis of Russell 3000 companies that IPO’d after 2010, 41% of scheduled vesting events occurred while the stock traded below its grant price.
– The Price-Protected RSU keeps everything about a traditional RSU the same, except one thing: at each vest date, the tranche only vests if the stock price has held at or above the grant-date price.
– Missed tranches aren’t forfeited outright. They carry forward and remain eligible to vest later. Most eventually would have vested in the same analysis noted above; only 16% were ultimately forfeited assuming a three-year quarterly design with a two-year grace period.
– The design flexes by population: longer grace periods and carry-forward windows for broad-based grants, tighter parameters for executive awards.
The memo notes that for many companies, automatic vesting will still be the best approach. But for others, a modest amount of built-in flexibility may better align equity design with shareholder expectations, employee outcomes, and long-term program objectives. Always make sure to consider the accounting and legal implications if you are making a change!
FW Cook recently published its annual incentive plan report – which reviews plans at the top 250 largest S&P 500 companies by market cap, based on 2025 practices disclosed in 2026 proxy statements. Here are a few key highlights:
Core annual incentive design features have remained broadly stable over the last four years, including the prevalence of formulaic plans, the number and types of financial metrics, and the weighting of financial and non-financial measures.
The more notable changes are within the non-financial component. Team-wide strategic goals are more common than four years ago, individual performance goals are less common, diversity and inclusion measures have declined sharply, and artificial intelligence is beginning to appear explicitly in plan design.
Goal-setting showed more movement in 2025. More companies held revenue and profit targets close to prior-year actual performance, while threshold-to-maximum performance ranges widened. Those observations do not necessarily indicate easier goals: among companies with revenue goals and available beginning-of-year guidance, 61% set incentive-plan revenue targets above the guidance midpoint, and the median target across the full available sample was 0.4% above the midpoint.
Median CEO annual incentive payout for 2025 was 127% of target, in line with the 2023 median and below the 2021 median.
The report found that approximately 10% of the sampled companies that used team wide strategic measures disclosed an AI-related team-wide objectives. Here’s more detail on that topic:
• Most AI-related objectives were embedded within a broader strategic goal; two companies used AI as a stand-alone weighted metric. An additional ten Top 250 companies included AI-related performance within individual goals for select NEOs and are not included in the team-wide prevalence below.
• Almost all identified AI-related measures were assessed qualitatively rather than against defined quantitative goals; the two stand-alone AI metrics were assessed quantitatively.
• Current proxy disclosure may understate adoption because 2026 proxy filings generally report goals set for 2025; 2027 filings will provide greater visibility into AI-related goals adopted for 2026.
The report gives supplemental details by sector – which are worth reviewing since practices can vary across industries. It also identifies the companies included in the study.
You can still register to attend today’s conference and receive access to the archive of yesterday’s program as well as live and archived access for today! You can do that online or by calling us at 800-737-1271. Our conferences are bundled together into a single two-day event for registration and pricing, so your purchase will cover both events.
– How to Attend Online: Our conferences are hosted online through the RingCentral Events platform. When you register for the conferences, you’ll receive a registration confirmation email that will contain your personalized “Magic Link.” Just click on that link to be instantly directed to the event. The Magic Link acts as an “access pass” into the event. It is unique to you and cannot be shared with others. It bypasses the need for registered users to sign into RingCentral Events and brings you directly into your RingCentral Events account and into the event.
Once in the event, click the “Stage” button from the menu on the left of the webpage. In order to view the session currently playing on stage, you will need to press the play button on the video. If you’re having issues accessing the RingCentral Events platform, review this guide and contact your IT department. For audio/video issues, there are separate guides for Windows and for Mac. If you still need help, email info@ccrcorp.com.
– Access to Archives & On-Demand CLE: Your registration includes access to the conference archives, which will be available until October 12, 2027 – but you’ll need your confirmation email to access them so be sure to retain it! One big reason to make sure you do that is that if you can’t attend the conferences live, you may earn on-demand CLE credit by viewing the archives. See these “CLE FAQs for Archived Conference Sessions (ON DEMAND)” for more information.
– Thanks to Our Sponsors! A huge “thank you” to our sponsors who have helped make these events possible. Our founding sponsor for this year’s conferences is Goodwin, our PDEC lounge sponsor is Greenshoe.ai, our managing partner sponsor is Cooley, our associate sponsors are Ashurst Perkins Coie, Ballard Spahr, King & Spalding, Latham & Watkins, Morrison Foerster, Sidley, Troutman Pepper Locke, and Wilson Sonsini – and a special shoutout to our rise and shine breakfast sponsors Cleary and Dragon GC.
We are extremely grateful for the support of these fine law firms and businesses and invite you to consider joining them as a sponsor of next year’s conferences.”
John is going all out with his pithy quotes in his blogs on TheCorporateCounsel.net, and since I have already played up the Disney angle, I’ll leave you with the words of another well-known Floridian:
“It’s been a lovely cruise.” – Jimmy Buffett
Thanks to everyone who has participated in our Conferences this year!
I’m thrilled to be joined by so many of you in Orlando and virtually this week! We’re kicking things off today with our “Proxy Disclosure Conference” and we’ll follow that up tomorrow with our “23rd Annual Executive Compensation Conference.” The agendas for our conferences include 13 substantive panels over 2 days – and we’ll get started in style with Dave Lynn’s interview of Christina Thomas, Deputy Director of the SEC’s Division of Corporation Finance and Chief Advisor on Disclosure, Policy, and Rulemaking.
We’re very excited to see everyone in Orlando, but if you can’t be here in person, you can still register to attend today’s program and tomorrow’s “23rd Annual Executive Compensation Disclosure Conference” online or by calling us at 800-737-1271. Our conferences are bundled together into a single two-day event for registration and pricing, so your purchase will cover both events and you’ll get access to the archived programs for a year afterwards.
– How to Attend Online: Our conferences are hosted online through the RingCentral Events platform. When you register for the conferences, you’ll receive a registration confirmation email that will contain your personalized “Magic Link.” Just click on that link to be instantly directed to the event. The Magic Link acts as an “access pass” into the event. It is unique to you and cannot be shared with others. It bypasses the need for registered users to sign into RingCentral Events and brings you directly into your RingCentral Events account and into the event.
Once in the event, click the “Stage” button from the menu on the left of the webpage. In order to view the session currently playing on stage, you will need to press the play button on the video. If you’re having issues accessing the RingCentral Events platform, review this guide and contact your IT department. For audio/video issues, there are separate guides for Windows and for Mac. If you still need help, email info@ccrcorp.com.
– Access to Archives & On-Demand CLE: Your registration includes access to the conference archives, which will be available until October 12, 2027 – but you’ll need your confirmation email to access them so be sure to retain it! One big reason to make sure you do that is that if you can’t attend the conferences live, you may earn on-demand CLE credit by viewing the archives. See these “CLE FAQs for Archived Conference Sessions (ON DEMAND)” for more information.
– Thanks to Our Sponsors! A huge “thank you” to our sponsors who have helped make these events possible. Our founding sponsor for this year’s conferences is Goodwin, our PDEC lounge sponsor is Greenshoe.ai, our managing partner sponsor is Cooley, our associate sponsors are Ashurst Perkins Coie, Ballard Spahr, King & Spalding, Latham & Watkins, Morrison Foerster, Sidley, Troutman Pepper Locke, and Wilson Sonsini – and a special shoutout to our rise and shine breakfast sponsors Cleary and Dragon GC.
We are extremely grateful for the support of these fine law firms and businesses and invite you to consider joining them as a sponsor of next year’s conferences.
Make sure to say hi if you’re here in person – and if the mood strikes, post a selfie or two on LinkedIn!
Yesterday, ISS announced the results of its latest annual global Benchmark policy survey, which asked participants several compensation-related questions. For example, the survey asked for input on how to signal significant concerns about executive pay when no say-on-pay vote is on the ballot, given that more companies may be exempt from holding this vote if the SEC’s “Filer Status” rule changes are adopted as proposed. The press release summarizes the answers to that question as follows:
Fifty percent of investor respondents said that where pay concerns and a say-on-pay vote is not on the ballot, they would support in the first year opposing the election of the chair of the compensation committee, and a further 41 percent of investor respondents supported opposing all incumbent compensation committee members. Among non-investor respondents, 54 percent of non-investor respondents said opposition of compensation committee members would not be appropriate under such circumstances.
The survey also addressed several other U.S. compensation topics. Here’s a brief summary of the input ISS received on those matters:
As a follow-up, the survey asked what level of support for compensation committee members should be considered a low vote that triggers ISS’s responsiveness policy. (Currently, there’s a 50% director election threshold and a 70% say-on-pay threshold.) Most investor respondents (67%) favored the 70% threshold applying for purposes of assessing whether the responsiveness policy has been triggered. Only 26% of non-investor respondents supported the 70% threshold. 46% of non-investor respondents supported the 50% threshold.
Investor and non-investor respondents differed on whether financial services companies’ discretionary bonus programs should receive special, sector-specific treatment rather than being treated generally as a concern in the pay-for-performance evaluation, with 85% of non-investors saying financial services discretion-based bonus programs should not be viewed as a concern, while 71% of investor respondents said they should continue to be treated as concerning. However, more than 80% of both groups agreed that disclosures — like pre-set pay opportunities, performance category or factor weightings plus explanations regarding payout determinations — could mitigate concerns.
Finally, the survey also asked whether and when the risk of competitive harm constitutes a compelling rationale for not disclosing forward-looking LTI performance targets, and specifically whether it’s less compelling for relative than for absolute metric goals. For investors, the most common response (50%) was that this could be a reasonable rationale but should be assessed on a case-by-case basis. Non-investor respondents most commonly (49%) thought the risk of competitive harm is a reasonable rationale for non-disclosure by any company. Some respondents (21% of investors and 31% of non-investors) thought the risk of competitive harm may be a compelling rationale if the company commits to retrospective disclosure. That same number of investor respondents (21%) thought competitive harm is not a reasonable rationale in most or all cases. Investors largely (79%) considered the rationale more compelling for absolute versus relative performance metrics, while non-investors were evently split.
See Liz’s blog on TheCorporateCounsel.net for the results of the governance-related survey questions.
This month last year, Glass Lewis announced that it will be moving away from “singularly-focused research and vote recommendations based on its house policy.” Last month, the proxy advisor announced that it has now opened a comment period on the four perspectives that will underpin its research beginning in September 2027 and is soliciting feedback from both institutional investor and corporate stakeholder groups. Pay Governance recently released a viewpoint regarding how this shift is likely to impact say-on-pay votes.
The four perspectives share a common compensation foundation. All perspectives maintain core expectations around reasonable pay levels, pay-for-performance alignment, disclosure quality, severance practices, incentive design, non-employee director pay programs, and other key governance topics.
The major differences among the models lie in how the perspectives may weigh performance, sustainability, and stakeholder outcomes. Business Fundamentals could treat top-quartile relative TSR as an explicit mitigating factor, allowing greater tolerance for higher pay or certain design features. Sustainability Focused may instead expect material sustainability considerations in performance measurement and assess whether pay outcomes align with the broader stakeholder experience. Thus, a company’s Say on Pay proposal may draw different recommendations—particularly when pay is high, relative TSR is strong, sustainability metrics are absent, or stakeholder and executive outcomes diverge [. . .]
The proposed Glass Lewis pivot on advisory reports changes the lens through which programs are viewed, but not the fundamentals. Compensation committees should continue to design pay to align with business strategy, performance, and long-term value creation, supported by rigorous governance and an investor-informed rationale. The best-positioned companies will not attempt to tailor their programs to each Glass Lewis perspective; rather, they will understand their shareholders and explain why their programs are right for their business.
It reiterates that this announcement is part of a broader trend where “investor policies—and not one proxy advisor standard—may increasingly drive voting decisions.” It also notes that pay disclosure may be fundamentally transformed by proposed and expected SEC rulemaking that could reduce and streamline required disclosures—and even make many more companies eligible for scaled disclosure and other accommodations, like omitting a say-on-pay proposal. This could raise the stakes for some companies (if investors voice their perspectives through “withhold” votes on compensation committee members, for example) and increase the need to provide more context and address more perspectives in your disclosures, even as disclosure requirements become less prescriptive.
As Liz shared on TheCorporateCounsel.net yesterday, Walt Disney World celebrated its 55th anniversary last week and marked the occasion by looking back at what it has been through since 1971 and how much has changed along the way. Through all of it, the magic has endured! That feels on point for those of us working in corporate governance and executive compensation as well. So the timing is right to gather at our 2026 Proxy Disclosure & 23rd Annual Executive Compensation Conferences next Monday and Tuesday, October 12th and 13th (less than one week away!), in Orlando and virtually, to discuss perennial issues plus the many regulatory and market developments companies are navigating right now. Getting together with a group of people with a shared passion for corporate governance, quality disclosure and pay-for-performance always feels magical to me!
Here’s a look at some of the hot topics our experienced speakers will be addressing. You’ll walk away with a better understanding of the practical impact these developments may have on companies, disclosures and boards – and how all the moving pieces fit together.
On October 12th, our 2026 Proxy Disclosure Conference will focus on (you guessed it) proxy disclosures – starting with an interview with Corp Fin Deputy Director Christina Thomas. Among other topics, we’ll discuss the fate of shareholder proposals, the current shareholder activism environment, common mishaps (and how to avoid and resolve them), tokenization of securities and other market developments, SEC proposals on registered offering reform and filer status, shareholder engagement and voting, and advising boards during times of uncertainty.
On October 13th, our 23rd Annual Executive Compensation Conference turns to (yep!) executive pay, including potential changes to the SEC’s compensation disclosure rules, the potential expansion of scaled disclosure, equity design (including long-vested RSUs), special awards, executive and director pay trends, and perks and executive security. We will close the conference with the popular panel “Navigating ISS & Glass Lewis” featuring a practical conversation with representatives from both proxy advisors on disclosures and practices that will help (or hurt) your cause on say-on-pay, compensation committee elections and equity incentive plan approvals, moderated by Davis Polk’s Ning Chiu.
For those attending in person, the magic actually starts a little early! We’ll have a welcome reception Sunday, October 11th, from 4:30–6:00 p.m. in the Orange Foyer. And the networking opportunities continue on the evening of the 12th at the NASPP opening celebration immediately after Monday’s programming.
As always, the two days are bundled together, and you can join us in person at the Hilton Orlando or virtually. And in addition to live and on-demand access to all of the CCRcorp sessions, Conference attendees get exclusive access to our Course Materials – which are up on the conference platform and app now and include unique & practical bullet points on the topics our speakers will be covering. The Course Materials and on-demand replays are invaluable resources to refer back to as proxy season approaches!
Act Now: The Conferences begin next Monday, October 12th. With 14 sessions over 2 days, you’ll walk away with action items to help support director elections and say-on-pay, see around corners for changes to rules and market mechanics that affect companies, and avoid costly mistakes. You can still register. Sign up online, email info@ccrcorp.com or call our team at 800-737-1271 today.
Lastly, if you have registered, remember that your unique access link and attendance instructions will be emailed to you from no-reply@events.ringcentral.com. Here’s more detail on what to watch for.
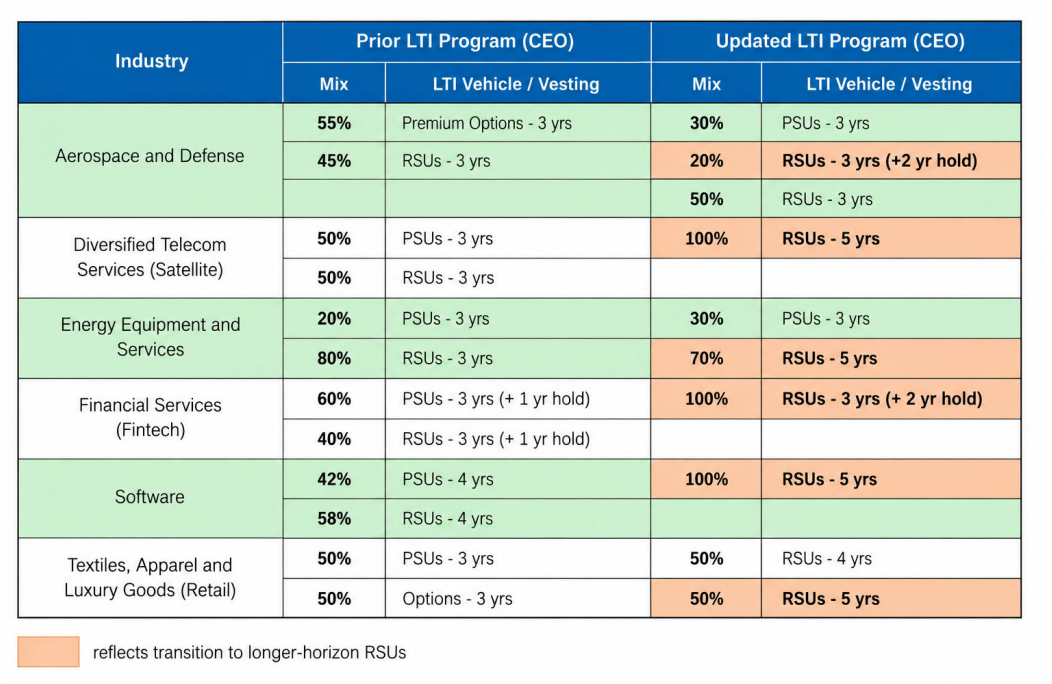
With ISS’s latest policy updates loosening the proxy advisor’s preference for at least 50% of LTI in PSUs as long as time-based equity meets its long-term parameters, we already knew that some companies have been considering making a change. FW Cook reviewed forward-looking disclosures in 2026 proxy statements to see if any companies have already committed to taking the plunge. They found at least six companies that have already disclosed a transition, as summarized below.
They highlighted a few considerations and takeaways from these early movers:
– Many of them had one thing in common: they are in cyclical, seasonal or volatile businesses.
– Companies shouldn’t think of the decision as a binary one. Reducing PSU weighting and introducing longer vesting RSUs might be the right first move for some companies.
– The shift can create vesting gaps, and companies should model the transition for each executive to understand the impact.